When starting or growing a retail business, one of the first key decisions is selecting the right legal structure. Should you operate as a limited company, or would a partnership better suit your needs? While this may seem like a straightforward choice, the decision directly affects tax obligations, liability, management, and the long-term success of your business.
The structure you choose impacts how profits are shared, how decisions are made and how easily you can raise funds or bring in new shareholders or partners. For retail businesses, where sales margins, growth potential and customer experience are critical, having the right foundation can make a significant difference.
In this blog our Corporate Lawyers and Retail Experts set out the key differences between partnerships and limited companies, and explains what each structure means in practice for retail owners.
Overview of General Partnerships
A general partnership can be formed automatically by carrying on business with another person for the purpose of making a profit.
In general partnerships, all partners share responsibility for operational management and bear unlimited personal liability. This is a significant drawback as it means that the personal assets of partners may be at risk if the partnership business encounters financial difficulties. However, the simplicity of the formation of a general partnership is a major advantage, especially for entrepreneurs, given the low set up costs and minimal formalities.
Overview of Private Limited Companies
Limited companies, by contrast, are separate legal entities distinct from their owners or shareholders. This allows a company to own assets, enter into contracts and be held liable for its debts. The shareholders of a private company enjoy limited liability, in that their personal exposure to the liabilities of the company is limited (in the absence of any other specific arrangements being put in place) to the amount they have contributed in share capital.
With a company, ownership (the shareholders) and management (the directors), are separated. The shareholders effectively delegate the day to day running of the company to the directors. Typically, in many smaller companies the shareholders and directors can be the same people.
Incorporating a limited company in the UK involves a number of formalities that, while manageable, can be more extensive than many first-time business owners anticipate. From choosing a unique company name and registered office address, to appointing directors and issuing shares, each step requires careful legal and administrative attention. Key documents such as the Memorandum and Articles of Association must be prepared, and compliance with the Companies Act 2006 and registration with Companies House are mandatory. Once the company has been incorporated, there are ongoing obligations which include filing annual accounts and confirmation statements and also registering for Corporation Tax with HMRC. Although online registration has simplified the process, the legal and compliance requirements remain substantial, especially for those unfamiliar with company law. Seeking professional advice is therefore recommended to ensure all aspects are handled correctly and efficiently.
Limited companies tend to project a more professional image, a company’s share capital provides an attractive structure for investment and companies also benefit from business continuity regardless of changes in ownership.
The main disadvantage of a company is the increased administrative burden and cost compared to partnerships, which can be time-consuming and may require professional assistance. Additionally, there is less privacy for a company, since information such as director details and financial accounts are publicly available at Companies House.
Taxation
The tax regime which applies to general partnerships and limited companies is different. Companies pay corporation tax on its profits and the partners of a partnership pay income tax. Therefore tax advice is essential when deciding on the best business structure to be adopted.
Legal Implications for the Retail Sector
As outlined, the difference in liability between partnerships and limited companies has significant consequences for retail businesses. Retailers operating as partnerships face greater personal financial risk, which can hinder their ability to seize new opportunities or recover from setbacks like stock loss or customer claims. In contrast, limited companies benefit from limited liability, giving retail owners confidence to invest, expand, and manage risks without jeopardising their personal finances. This often makes limited companies the preferred choice for retailers seeking long-term security and growth potential.
Our Corporate Solicitors at Myerson offer expert guidance on the various business structures available, ensuring that your company’s specific requirements and objectives are thoroughly considered. We provide tailored advice designed to help you make informed decisions that safeguard your interests and promote sustainable growth.
Contact Our Retail Solicitors
For tailored advice on choosing the right legal structure for your retail business, contact our Corporate Team and Retail Experts on:
0161 941 4000
More Retail Law News and Advice
Can a Court Save a Retailer? The TG Jones Judgment Shows the Limits of Restructuring
On 1 July 2026, the High Court approved TG Jones' restructuring plan - but the judge (Mr Justice Hildyard) openly questioned whether the turnaround would succeed. Our Insolvency and Restructuring team explore what the Court’s decision in this case tells us about the current restructuring regime in England and Wales.
Read Blog
What Due Diligence Is Required for a Commercial Property Purchase?
Purchasing a commercial property can deliver strong returns, whether through rental income received from tenants or long-term capital growth. It does, however, entail a range of legal and practical risks that, if not addressed and managed before exchange of contracts, can significantly affect the property’s value. Our Commercial Property team...
Read Blog
A Corporate Law Checklist for Founder-Led Retail Businesses in the UK
Running a founder-led retail business in 2026 often means making high-stakes decisions with limited resources while navigating changing costs, shifting consumer demand, and rising regulatory pressure. A solid grasp of core corporate law principles - such as governance, directors’ duties, fundraising, transactions, and ESG – can, however, help you...
Read Blog
Commercial Lease Legal Updates 2026: What Retail Tenants Need to Know
As we approach the end of the second month of 2026, we look at some of the changes that retail tenants can expect during the remainder of this year and beyond. From major changes to rent review mechanisms to business rates reforms and stricter energy performance standards, these updates will all impact retailers. It is important to be aware of...
Read Blog
Structuring Retail Businesses: Choosing Between a Limited Company or Partnership
When starting or growing a retail business, one of the first key decisions is selecting the right legal structure. Should you operate as a limited company, or would a partnership better suit your needs? While this may seem like a straightforward choice, the decision directly affects tax obligations, liability, management, and the long-term...
Read Blog
Budget 2025: The Impact on Hospitality and Leisure and Retail Businesses
On 26 November 2025, the Chancellor of the Exchequer, Rachel Reeves, delivered her second budget. In this blog, our Hospitality and Leisure and Retail lawyers explore the impact the budget will have on hospitality, leisure, and retail businesses, which have been facing mounting financial pressures in recent times.
Read Blog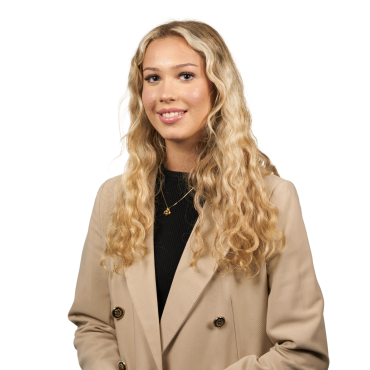
Alexia Dirgau
Trainee Solicitor
Alexia joined Myerson in 2022 as a Solicitor Apprentice and has been developing her legal knowledge and practical experience alongside her studies at BPP University. Her apprenticeship has provided her with a unique opportunity to learn through hands-on experience, working closely with colleagues across the firm while progressing towards qualification as a solicitor.
Alexia spent her first year in the Business Services team, where she gained valuable insight into how a law firm operates and developed a strong understanding of the importance of collaboration and client service. This experience provided an excellent foundation for her legal career and helped her build skills that she continues to apply in her work today.
Since then, Alexia has completed seats in Commercial Property, Commercial Litigation and Corporate, giving her exposure to a broad range of legal matters and allowing her to develop experience across both transactional and contentious work. These seats have helped her build a well-rounded understanding of the legal and commercial issues faced by individuals and businesses.
Alexia is currently undertaking a seat in the Probate Litigation team, assisting on a variety of contentious trusts and estates matters, including inheritance disputes and challenges relating to wills and estates. She particularly enjoys the variety of the work and the opportunity to help clients navigate what are often complex and sensitive situations.
One of the aspects Alexia enjoys most about her role is the collaborative nature of legal practice. She enjoys working closely with colleagues across different teams, drawing on a range of expertise to provide practical solutions for clients. Working alongside talented lawyers in a supportive environment has enabled her to develop both professionally and personally throughout her apprenticeship.
About Alexia Dirgau