Bankruptcy is a formal legal process designed to help individuals who are unable to repay their debts. Unlike companies or partnerships, only individuals can be declared bankrupt.
Our Personal Insolvency Lawyers provide a comprehensive overview of how bankruptcy works, the key procedures involved, and the implications for both debtors and creditors.
Understanding bankruptcy is essential for those facing financial difficulties or creditors considering insolvency action, as it carries significant legal and financial consequences.
What is Bankruptcy and How Does it Work?
There are three main ways in which an individual can be made bankrupt:
- An individual can apply to make themselves bankrupt. Here, the individual makes a bankruptcy application which is determined by an adjudicator through a government online portal (and not by the court).
- One or more of the individual’s creditors can apply to the court for a bankruptcy order. Presently, creditor(s) can apply for an individual to be made bankrupt if they are individually or jointly owed £5,000 or more in respect of a debt that is not disputed.
- The supervisor of a failed individual voluntary arrangement may present a bankruptcy petition to the court.
Administration of a Bankruptcy Estate
The administration of a bankruptcy estate is carried out either by the Official Receiver or by an insolvency practitioner and they are known as the trustee in bankruptcy. When a person becomes bankrupt, their assets (with certain exceptions) pass to the trustee in bankruptcy whose function is to realise those assets and distribute the proceeds to creditors (after payment of the costs for dealing with the bankruptcy) and in a prescribed order of priority.
An interest in assets can be realised in one of three ways:
- A third party can purchase the interest;
- The bankrupt can sell the asset and pay over the proceeds to the trustee; or
- The trustee can take possession of the asset to sell it. This option is likely to require expensive court intervention.
Unfortunately, if the bankrupt has no or limited assets, it is unlikely that creditors will get their money back.
If the bankrupt has surplus income above their needs and those of their dependents, the bankrupt may be required to pay that surplus income over to the trustee for the benefit of the bankruptcy estate. Such income payment agreements or orders can last up to 3 years.
There are also powers available to the trustee enabling them, in certain circumstances, to claim assets from third parties where they have been transferred to those parties for no consideration or at an undervalue or where creditors have been paid in preference to other creditors prior to the bankruptcy.
Restrictions on Bankrupt Individuals
The bankrupt can carry on their business and continue to work but with the following restrictions:
- The bankrupt must not obtain credit of more than £500 from anyone without telling that person that they are an undischarged bankrupt.
- The bankrupt must not act as a director of a company or be involved in its management without the court’s consent.
- The bankrupt must not carry on business under a name different from that under which they were declared bankrupt without disclosing the fact that they are an undischarged bankrupt.
It is a criminal offence for a bankrupt to break these restrictions.
Special Rules Regarding Residential Property
There are special rules regarding the property in which the bankrupt, their spouse or former spouse lives at the date of the bankruptcy order.
The bankrupt’s interest in the property vests in the trustee when the bankruptcy order is made and the trustee then has 3 years to deal with the bankrupt’s interest in the property.
If the trustee does not do so within this timescale, the interest in the property reverts back to the bankrupt.
Usually, a third party agrees to purchase the trustee’s interest in the property or the trustee has to make an application to the court for the possession and sale of the property.
Impact of Bankruptcy on Credit and Financial Opportunities
Bankruptcy significantly impacts credit scores, making it difficult to obtain loans, credit cards, and it can even affect insurance premiums and employment opportunities.
Conclusion
Bankruptcy is a significant and often complex legal step with far-reaching consequences for individuals facing financial difficulties. It is essential to consider all options and seek expert advice before proceeding.
For individuals struggling with debt, professional guidance can help determine if bankruptcy is the most appropriate solution. Similarly, creditors should consult with a solicitor to assess whether pursuing bankruptcy is likely to achieve a practical recovery of debts. Understanding the process and implications of bankruptcy ensures informed decisions that protect your financial and legal interests.
Contact Our Bankruptcy Lawyers
If you’re dealing with overwhelming debt or considering bankruptcy as a potential solution, understanding your options is crucial. Likewise, if you're a creditor seeking to recover debts, timely legal advice can help you navigate the insolvency process effectively.
At Myerson Solicitors, our experienced insolvency team provides tailored advice to individuals and creditors alike. We’re here to help you make informed decisions with confidence, compassion, and clarity.
0161 941 4000
More Personal Insolvency News and Advice
A Practical Guide to Bankruptcy Validation Orders
Our Personal Insolvency team look at the effect of section 284 of the Insolvency Act 1986 ( the Act ) regarding dispositions made by an individual in the period between the presentation of a bankruptcy petition (or making of a bankruptcy application) and the vesting of the individual’s estate in their trustee in bankruptcy. We also provide...
Read Blog
What Happens If Someone Who Is Bankrupt – Or About to be Made Bankrupt – Dies?
Losing a loved one is difficult enough without having to worry about debts, bankruptcy or legal processes. The good news is that the law in England and Wales sets out clear rules about what happens if someone who is bankrupt – or facing bankruptcy – dies, and those rules are designed to bring certainty at a stressful time. Our Personal Insolvency...
Read Blog
What Happens If HMRC Files a Bankruptcy Petition Against You?
If you have received a bankruptcy petition from HMRC, or have been warned that one is coming, the consequences can be life-changing. Your assets, home, business interests and professional status may all be affected. Our insolvency solicitors act for business owners, professionals and other individuals across England and Wales who face bankruptcy...
Read Blog
What Happens to the Family Home When Someone Is Made Bankrupt?
Our Personal Insolvency Lawyers explain what happens to the family home when someone is made bankrupt and how the trustee may deal with it. When an individual is made bankrupt, the bankrupt’s interest in the family home vests in the trustee in bankruptcy, whose duty it is to realise that interest for the benefit of creditors. As part of this...
Read Blog
Guide to Individual Voluntary Arrangements (IVAs)
An Individual Voluntary Arrangement (IVA) is a legally binding agreement that allows individuals struggling with unsecured debts to reach a settlement with their creditors. As an alternative to bankruptcy, it offers greater flexibility and can help individuals protect their assets while managing repayments. Our Personal Insolvency Lawyers outline...
Read Blog
Guide to Bankruptcy: Understanding the Insolvency Process for Individuals
Bankruptcy is a formal legal process designed to help individuals who are unable to repay their debts. Unlike companies or partnerships, only individuals can be declared bankrupt. Our Personal Insolvency Lawyers provide a comprehensive overview of how bankruptcy works, the key procedures involved, and the implications for both debtors and...
Read Blog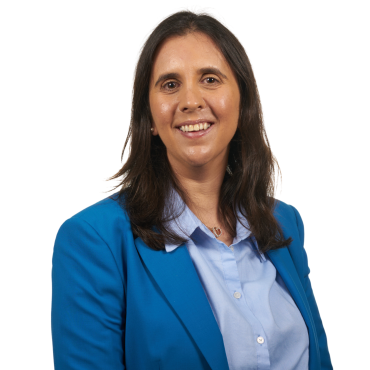
Vicky Biggs
Legal Director
Vicky is a Legal Director in the Insolvency and Restructuring team at Myerson and has been with the firm since 2012. Utilising her commercial litigation experience, Vicky now specialises in contentious insolvency matters, advising insolvency practitioners, directors and individuals in relation to both corporate and personal insolvency issues.
Vicky advises on a wide range of insolvency matters, including claims made by administrators, liquidators and trustees in bankruptcy, director disqualification proceedings, remuneration approval applications, retention of title claims, validation orders, bankruptcy annulment applications and winding-up and bankruptcy petitions.
About Vicky Biggs